Peloton Media Analysis Report
A Turnaround Still in Progress
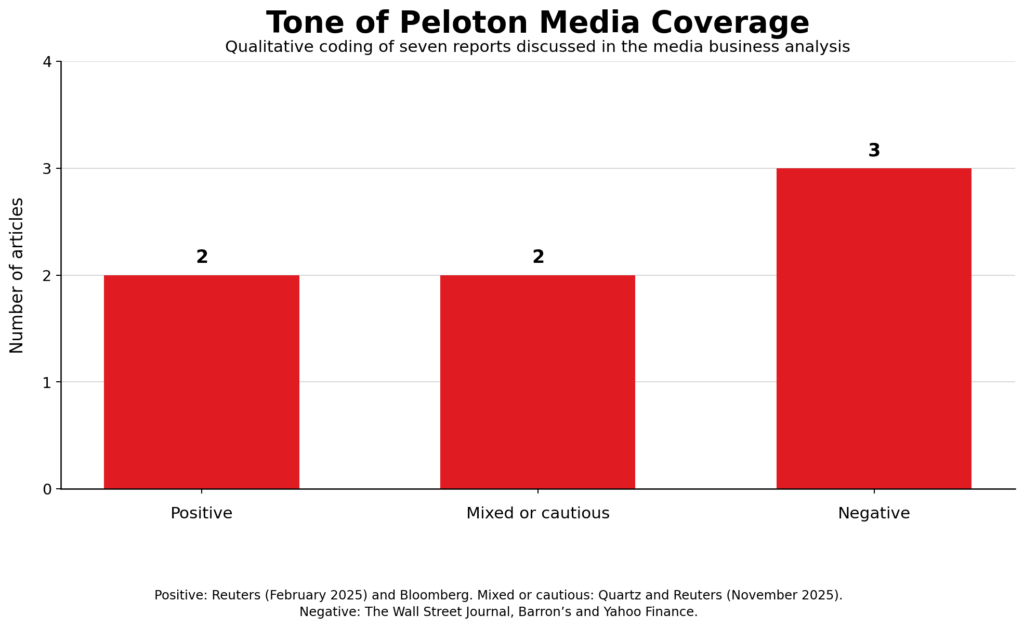
Peloton’s performance as of late has received mixed reviews with regards to financial performance and long-term growth. While some publications have focused on the company’s profitability, cost reduction and management efforts to return the company to stability, others have highlighted declining subscriptions, limited revenue growth and continued uncertainty around customer loyalty. For example, Reuters reported in February 2025 that the company had increased its profit forecast for the year, thanks to cost-cutting measures and growing subscriptions.
In a positive article published on May 7, 2026, Bloomberg reported that Peloton had raised its full-year outlook and was beginning to see the results of its turnaround strategy. The article cited stronger income projections, upgraded equipment, and increased commercial business among other factors. This positive coverage was followed by more cautious reporting after the company released its fiscal 2026 results on Aug. 6, 2026. Quartz reported that the company had earned $63.2 million in net income for the year, compared with a $118.9 million loss in the previous year. While this was the company’s first year of profitability, its revenue forecast for the year was weaker than expected and paid connected fitness subscriptions declined by 8.8%.
Subscriber Losses Complicate the Comeback
The Wall Street Journal reported on Peloton’s earnings in August 2026. The article reported that the company expected revenue to decline again in fiscal 2027 as paid subscriptions continued to decline. While earnings, gross margins and free cash flow increased, the article concluded that cost cutting for profitability would not be enough for investors if subscription and equipment sales continued to decline.
The Barron’s article from August 2026 followed the same theme. Although the company exceeded earnings expectations for the quarter, the stock fell as the company continued to experience declining sales. The article reported that the number of paid connected fitness subscriptions decreased by 8.8% for the quarter and said that fiscal 2027 could mark the sixth consecutive year of declining sales for the company. While the company is making progress towards profitability, investors are looking for more than short-term earnings and are questioning whether the company can rebuild its customer base and build loyalty with consumers.
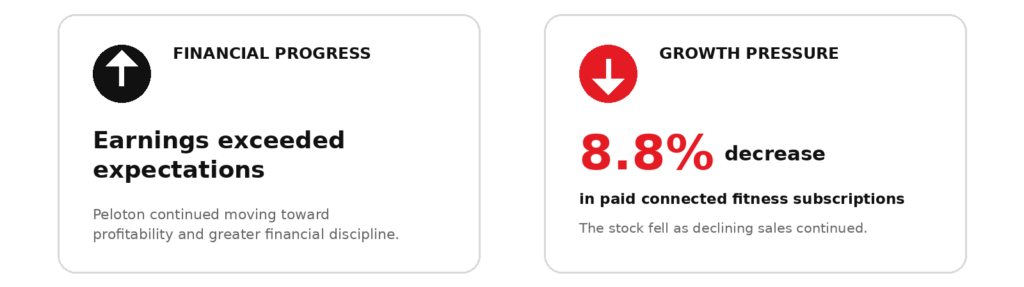
There is, however, evidence of progress on the part of Peloton’s financial performance. Financial analysts said in a Reuters article on Nov. 7, 2025, that they were “encouraged by Peloton’s progress across improving profit, ramping free cash flow, and deleveraging.” However, they also questioned whether the company’s product and marketing efforts would generate “durable revenue growth” in the long term.
Analysts Question Peloton’s Growth Potential
Morgan Stanley analyst Nathan Feather was much more pessimistic about the company’s prospects in a September 2026 note, in which he downgraded Peloton shares to Underweight from Neutral. In the note, which was reported on by Yahoo Finance on September 8, 2026, Feather said that expectations for a huge increase in customer additions were “highly unlikely,” and that “cheap is not a catalyst.” Instead, Feather said that the company’s low valuation would not be enough to drive investor support, and that the company’s problems were in part due to changing consumer fitness preferences, with people increasingly interested in strength training and gym memberships as opposed to home-based cardio machines like those offered by Peloton.
So while Peloton may be improving its finances in the short term, the larger growth issue remains unsolved. The positive reports highlight the company’s growing profitability, increasing free cash flow, and tightening of expenses. The negative reports on the other hand highlight the company’s declining subscriber numbers and decreasing revenue as well as the changing fitness preferences of consumers. Overall, the tone of the coverage remains cautious with some positive elements but is largely negative in nature as business reporters and analysts wonder whether the company can attract enough customers to sustain long term revenue growth.
References
Barron’s. “Peloton beat earnings, but the stock drops as sales continue to fall.” Aug. 6, 2026. https://www.barrons.com/articles/peloton-earnings-stock-price-10a89f96?
Bloomberg. “Peloton raises full-year outlook, signaling turnaround on track.” May 7, 2026. https://www.bloomberg.com/news/articles/2026-05-07/peloton-q3-2026-results-raises-forecast-suggesting-turnaround-on-track
Quartz. “Peloton posted its first full-year profit ever, but the stock sank on a weaker sales outlook.” Aug. 6, 2026. https://qz.com/peloton-first-annual-profit-fiscal-2026-sales-outlook-080626
Reuters. “Peloton raises 2025 core profit forecast as cost cuts, subscription push pay off.” Investing.com, Feb. 6, 2025. https://www.investing.com/news/stock-market-news/peloton-raises-2025-core-profit-forecast-as-cost-cuts-subscription-push-pay-off-3853647
Reuters. “Peloton shares jump as turnaround strategy gains traction.” Investing.com, Nov. 7, 2025. https://www.investing.com/news/stock-market-news/peloton-shares-jump-as-turnaround-strategy-gains-traction-4341563
The Wall Street Journal. “Peloton Interactive forecasts revenue decline as subscriber losses deepen.” Aug. 6, 2026. https://www.wsj.com/business/earnings/peloton-interactive-forecasts-revenue-decline-as-subscriber-losses-deepen-eacebb8d
Yahoo Finance. “Morgan Stanley cuts Peloton rating on structural fitness headwinds.” Sept. 8, 2026. https://uk.finance.yahoo.com/news/morgan-stanley-cuts-peloton-rating-122208362.html